NEXT is now ERGO NEXT Insurance, uniting digital-first innovation with Munich Re's global financial strength.

Business Insurance Texas

Save on small business insurance in Texas with discounts up to 25%.*

Choose your primary coverage to get started:

What could Texas business insurance help cover?

Damages to property

If your crew cracks a customer’s expensive countertop during installation of a stove, or a fire damages equipment at your Dallas workshop, the right business insurance in Texas coverage could help cover the costs.**

Workplace-related injuries (for customers and employees)

A visitor takes a tumble at your shop, or your employee suffers an injury on the job. Business insurance could help with medical bills and other covered expenses.

Inventory

Theft, burglary and vandalism

You arrive at your Austin job site to find your equipment broken or missing. Or you find broken windows and stolen inventory at your Plano storefront. Texas business insurance could help with costs and recovery.

Business income interruptions

Lost business income

A covered fire shuts down your San Antonio bakery, but rent and other expenses keep coming. Business insurance could help replace lost income and cover ongoing costs while you rebuild.

Professional mistakes that cause client financial loss

You deliver a project, but the customer says an error in your work caused a financial loss. Even if you disagree, defending your business can be expensive. Business liability insurance in Texas could cover legal expenses.

Legal fees and defense costs

An injured customer sues your business in Corpus Christi. Depending on the claim, business liability insurance in Texas could help cover the costs of your legal defense.

Is Texas business insurance required?

Some types of small business insurance in Texas are required by state law. Proof of business insurance can also be a requirement in the Lone Star State to:

  • Drive for business
  • Work in construction or as a contractor
  • Qualify for some professional licenses
  • Rent or lease a commercial building space for your business
  • Land a contract with some clients

Mandatory Texas Commercial Auto insurance requirements

If your business owns vehicles or you and your employees drive for work, make sure you’re meeting Texas’s minimum auto liability insurance limits, commonly known as 30/60/25 limits:

  • $30,000 for bodily injury per person
  • $60,000 for bodily injury per accident
  • $25,000 for property damage per accident

Some commercial cars, trucks, vans, trailers or other vehicles are required to carry higher limits.

Mandatory Texas business liability insurance requirements for licensed contractors

Some specific licensed contractor trades — like electrical contractors and HVAC contractors — must obtain and maintain specific business insurance coverage. See the Texas Department of Licensing and Regulation’s contractor requirements for details specific to your construction trade.

Remember that even if your profession doesn’t have a state-mandated insurance requirement, customers and project owners may require proof of coverage before they’ll hire you.

Texas Workers’ Compensation insurance requirements

The rules around workers’ comp for Texas business owners are unusual relative to most other states.

Contractors and subcontractors working on qualifying public building or construction projects must provide workers’ compensation insurance for employees working on those projects.

But beyond that, private employers aren’t legally required to carry workers’ compensation insurance. According to the Texas Department of Insurance, employers that choose not to carry coverage (called non-subscribers) must notify employees that they don’t have coverage. They must also file required notices with the Texas Division of Workers’ Compensation.

Those notices include workplace postings, written notification to new employees and reports to the state. Some employers are also required to report work-related injuries, illnesses and fatalities.

While not required in the state, without workers’ compensation coverage, employers may face employee injury lawsuits and lose important legal defenses.
How much does Texas small business insurance cost?

There’s no one-size-fits-all price for small business insurance in Texas. A self-employed bookkeeper in Lubbock, a landscaping company in Round Rock and a roofing contractor in Beaumont all face different risks, so it makes sense that their insurance costs would be different, too.

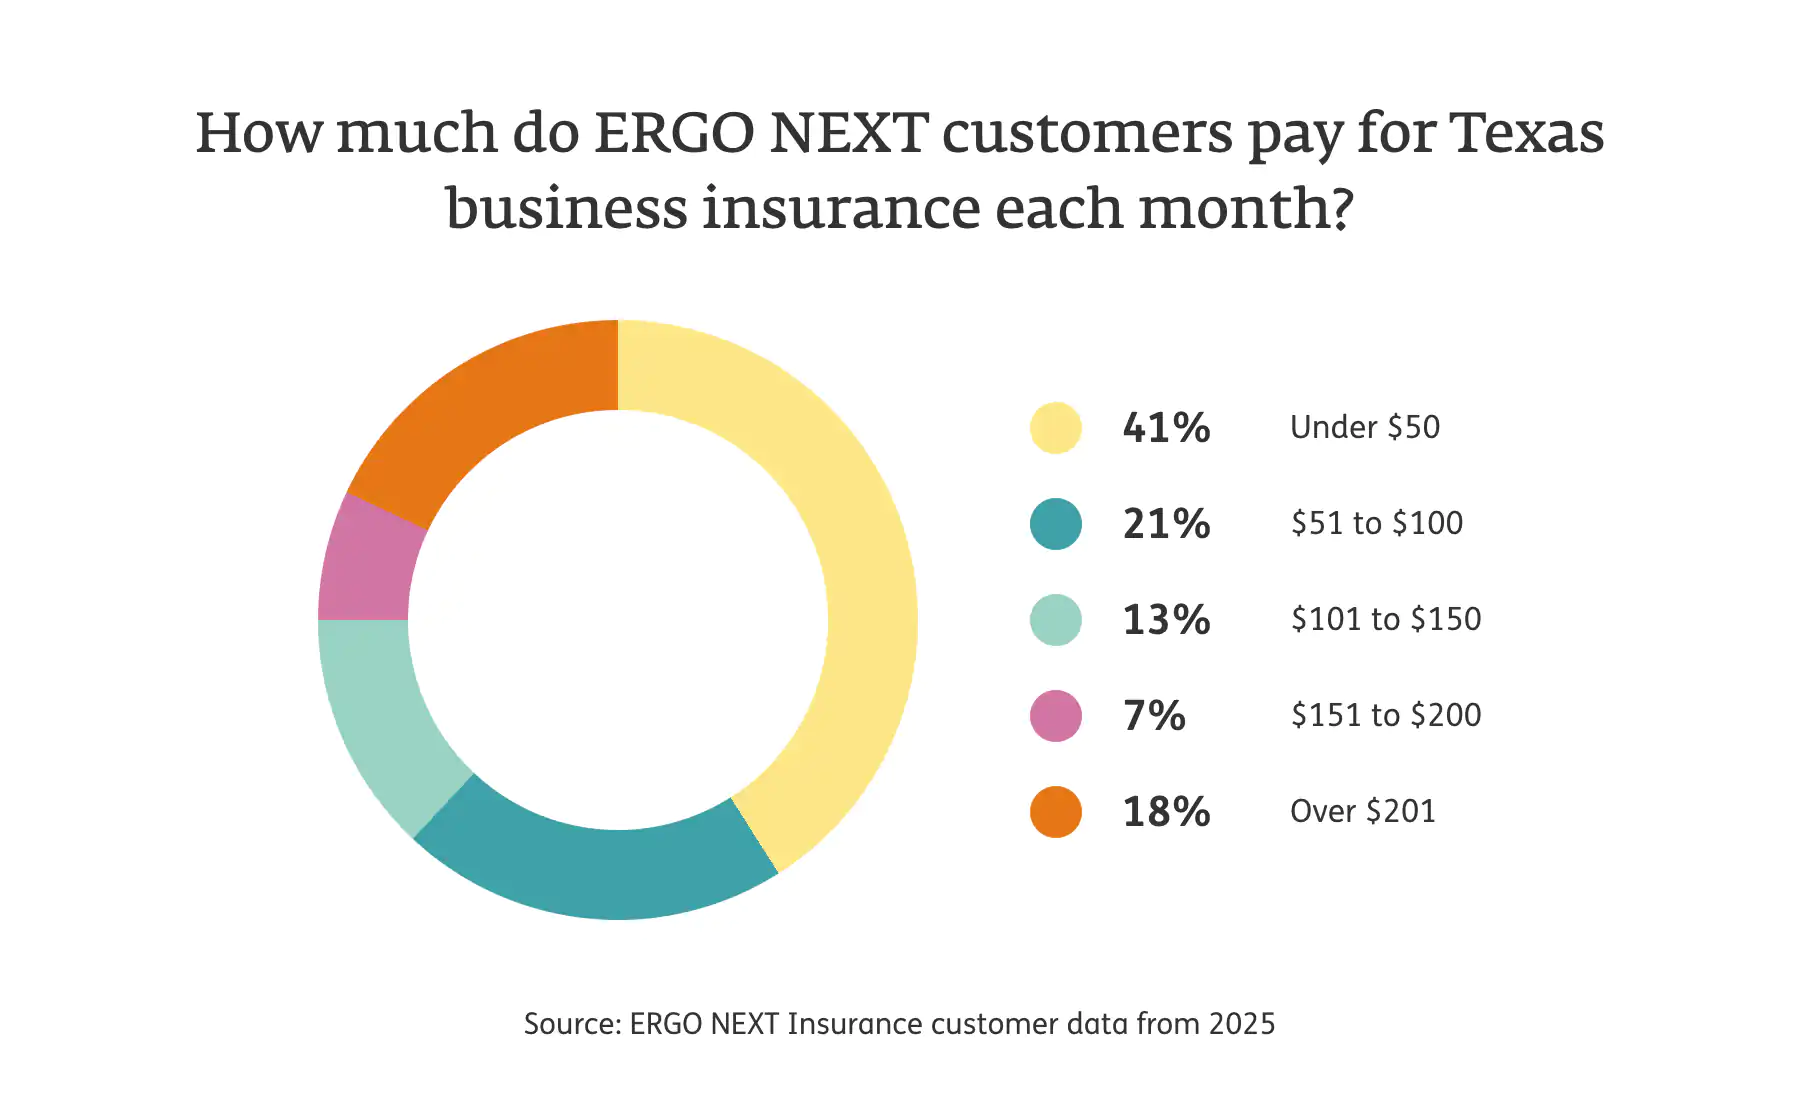
In 2025, 41% of Texas businesses insured through ERGO NEXT paid less than $50 per month for their total coverage, and 62% paid $100 or less.*** Some paid as little as $19 per month for a single policy.† 

For general liability insurance, the most common type of ERGO NEXT coverage in Texas, the median monthly premium was $64.

In 2025, 62% of Texas business owners insured through ERGO NEXT paid $100 or less per month for business insurance.

Several factors could influence the cost of your Texas small business insurance, including:

  • The kind of work you do. A commercial painter, independent accountant and neighborhood restaurant owner face different risks, which insurers consider when setting insurance premiums.
  • Your workforce. The number of employees you have, your payroll and worker job classifications can affect workers’ compensation costs.
  • Your location. Businesses near the Gulf Coast may face hurricane and windstorm exposure, while companies in North Texas may be more concerned about hail. Different risk exposure can impact your cost.
  • The property you own. A machine shop with expensive equipment or a retailer with substantial inventory may need more coverage than an accountant who works from home on a laptop.
  • Your business vehicles. How many vehicles you have, who drives them and how they’re used for work can all influence the price you pay for commercial auto coverage.
  • Your claims history. Previous losses and your record of workplace safety could affect the price you pay.
  • Your coverage choices. What kind of coverage you opt for, combined with your selected policy limits, deductibles and optional additional protections all contribute to the total cost.

The best way to find out what you’ll pay for small business insurance in Texas is to get a quote customized for what your business actually does and how it operates. With ERGO NEXT, you can check prices and buy coverage in about 10 minutes, 100% online.

Get Instant Quote

Which Texas business insurance policies do business owners buy most often?

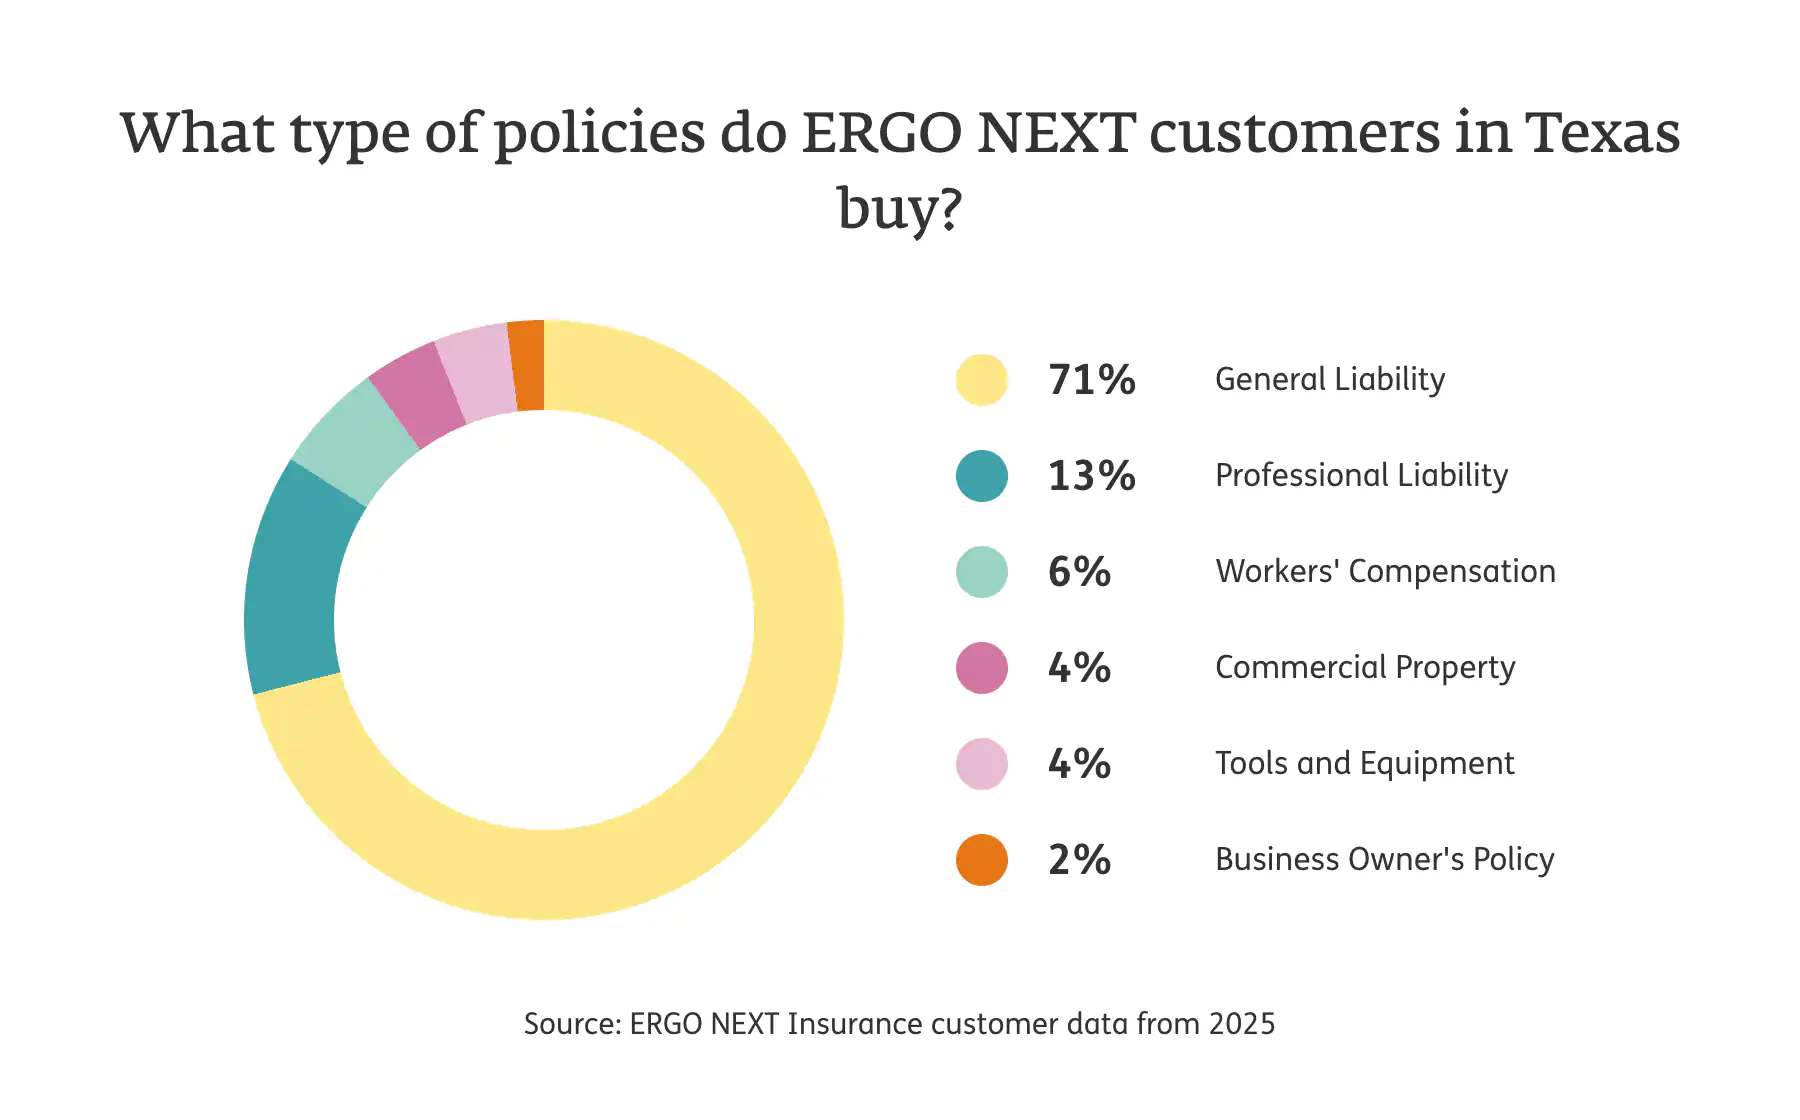
71% of the ERGO NEXT policies in force in Texas during 2025 were general liability insurance.

General liability is a common first policy for small businesses because it can provide coverage for a broad range of accidents and incidents. This includes

situations like injuries to non-employees and accidental property damage to the belongings of a customer, client or vendor.

The second most common type of small business insurance in Texas is professional liability insurance, also called errors and omissions insurance, or E&O. This type of policy could help protect you if a client claims that a professional error, mistake or omissions you made caused them financial harm. This policy is frequently sought after by people working in professional services, such as consultants, accountants, real estate professionals and the like.

71% of the ERGO NEXT policies in force in Texas during 2025 were liability insurance.¹

Which types of TX business insurance could benefit your business most?

The best Texas small business insurance coverage for you depends on what happens during a typical workday and what it might cost your business if something goes wrong. Here are six types of business insurance a small business should consider.

Texas General Liability insurance

General liability insurance could help if a non-employee is injured at your place of business, or you or your employees accidentally damage property that belongs to someone else.

For example, an appliance installer in Waco accidentally scratches a customer’s hardwood floors. If the homeowner seeks compensation, general liability insurance could help pay eligible costs.

If you work in cleaning or construction and your job takes you to different job sites, you may also want to add optional tools and equipment insurance to your general liability policy. This coverage could help cover gear that’s stolen or damaged while being transported or used for work.

Learn more about general liability insurance in Texas

Texas Workers' Compensation insurance

If a technician at a Midland equipment repair shop injures their hand while servicing machinery, workers’ comp could help cover eligible medical treatment and disability benefits while the employee recovers.

In general, workers’ compensation insurance could help pay medical expenses and replace a portion of an employee’s lost wages after a work-related injury or illness.

Although most private employers in Texas can choose whether to carry workers’ compensation, going without it could expose your business to employee injury lawsuits.

Learn more about workers’ compensation insurance in Texas.
Commercial Auto

Texas Commercial Auto insurance

If your business relies on vehicles, commercial auto insurance could help protect you financially after a covered accident.

Consider a landscaping truck in San Antonio that collides with another vehicle while heading to a job site. Depending on the policy, commercial auto insurance could help pay for eligible third-party injuries, property damage and repairs to the business vehicle.

When comparing TX commercial auto insurance options, consider the vehicles your company owns, who drives them and how frequently they’re used for work.

Businesses that rent vehicles or have employees drive their personal cars for work may also benefit from hired and non-owned auto coverage.

Note: Commercial auto isn’t offered through ERGO NEXT. ERGO NEXT partners with Progressive Insurance for commercial auto policies.

Learn more about commercial auto insurance.
Commercial Property

Texas Commercial Property insurance

You’ve invested a lot in your business inventory and equipment, as well as a storefront, office, home office, warehouse, manufacturing facility or other commercial building space. Commercial property insurance could help protect these assets after a covered loss.

Imagine a severe thunderstorm damages the windows of a furniture store in Tyler and excessive rainwater ruins merchandise. Depending on the policy, commercial property coverage could help pay for eligible costs.

Texas businesses should review their policies carefully for windstorm, hail and flood exclusions. According to the Texas Department of Insurance, most commercial property policies don’t cover flooding. And businesses along parts of the Gulf Coast may need separate windstorm and hail insurance.

Learn more about commercial property insurance in Texas.
Errors & Omissions

Texas Professional Liability insurance (Errors and Omissions insurance)

If clients hire you for your advice, consulting, or professional services expertise, even a small mistake can have expensive consequences.

Professional liability insurance, also called errors and omissions insurance (E&O), could help pay legal expenses and settlements if a client alleges that your professional error or negligence caused them financial harm.

For example, a Dallas marketing consultant makes an error in an advertising campaign that causes a client to lose a significant amount of money. If the client files a claim, professional liability insurance could help cover eligible defense costs.

General liability insurance typically doesn’t cover claims arising from mistakes in professional services, so businesses may need both types of protection.

Learn more about professional liability insurance in Texas.
Business Owner Policy

Texas Business Owner's Policy (BOP insurance)

A business owner’s policy bundles general liability insurance and commercial property insurance into one policy, often at a better price than buying both separately.

Think about a neighborhood pet supply store in Denton. The owner wants protection if a customer gets hurt inside the shop. But they also want to protect products and inventory, shelving and displays, lighting, furniture, flooring, computers and POS systems. A BOP could address both types of risk.

Learn more about a business owners’ policy in Texas.

Get custom business insurance with ERGO NEXT in about 10 minutes, 100% online

Why choose ERGO NEXT for small business insurance in Texas?

Why choose ERGO NEXT for small business insurance in Texas?

ERGO NEXT makes it easy to find small business insurance Texas owners can customize for the work they do. Get a free, no-obligation quote in about 10 minutes, 100% online.

Manage your policy 24/7 via web or mobile app, and get unlimited, sharable certificates of insurance (proof of insurance) at no extra cost.

If you have questions, our U.S.-based licensed agents are available to help.

Get Instant Quote

Business Insurance Texas FAQ

Here are answers to some of the most frequently asked questions about Texas business insurance requirements, coverage and costs.

What happens if a Texas business doesn't have required insurance?

If your business doesn't carry the business insurance that's required by law, you could face fines, licensing problems or other penalties. The consequences depend on which coverage you're required to have.

For example, electrical contractors and certain HVAC contractors must maintain minimum liability coverage. If that coverage lapses, they could face licensing penalties.

Driving a business vehicle without the required liability insurance could also result in fines or other penalties.

Workers' compensation is a bit tricky. Most private employers can legally choose not to carry workers’ comp, but they must comply with notification and reporting requirements. And if you opt out of coverage, you could face significant financial exposure if an employee is injured and files a lawsuit.

Even when coverage isn't legally required, going without business liabilityinsurance means that Texas business owners could pay out of pocket for injuries, property damage or lawsuits.

Is Workers' Compensation insurance required for small businesses in Texas?

Some businesses and projects, including qualifying public construction work, have mandatory workers’ comp coverage requirements.

But Texas allows many businesses to decide whether to purchase workers' compensation coverage, rather than making it a legal requirement across the board. 

If you choose to opt out, you must notify workers and file required notices with the state.

What does it mean to be a Workers' Compensation non-subscriber in Texas?

A non-subscriber in Texas is an employer that doesn't provide workers' compensation insurance to employees.

Non-subscribers must notify employees, post required workplace notices and file reports with the Texas Division of Workers' Compensation. Certain employers must also report work-related injuries, illnesses and fatalities.

The Texas Department of Insurance's non-subscriber guidance explains these requirements.

Does Texas require General Liability insurance for small businesses?

Texas doesn't require every small business to carry general liability insurance, but  some licensed professions, including electrical contractors and HVAC contractors, have specific requirements.

You may also need liability coverage to sign a lease, qualify for certain projects or satisfy customer contracts.

When comparing small business liability insurance options in Texas, check both licensing requirements and contractual obligations.

Does Texas business insurance cover hurricanes, hail and floods?

Commercial property insurance may help pay for windstorm or hail damage, but businesses in certain coastal areas may need separate insurance.

Flood damage is generally excluded from standard commercial property policies and typically requires separate coverage.

The Texas Department of Insurance explains these differences.

Can business insurance cover lost income after a hurricane or major storm?

Business income insurance, often a component of commercial property coverage, could help replace lost income if your business is forced to close temporarily as a result of covered damages. 

For example, if a covered storm damages a Fort Worth restaurant and repairs take several weeks, business income coverage could help with eligible lost income and some temporary expenses during the closure.

Does a home-based business in Texas need commercial insurance?

Your homeowners' or renters' insurance may only provide limited protection for business equipment, property and inventory if you run your business from home, and it usually excludes business liability claims. Texas small business insurance could help protect against the business risks that personal policies don't adequately cover.

What if my employees drive their own cars for my business?

Even if your employees are driving their insured personal vehicles for work, your business could still face liability exposure.

For example, a catering company whose staff deliver orders or a property manager whose employees drive to inspections could face claims arising from work-related accidents.

Hired and non-owned auto insurance could help cover certain liability claims involving vehicles your business doesn't own, but it generally doesn't replace your employee's personal auto policy or cover damage to their vehicle.

ERGO NEXT Insurance reviews

I am so excited
I am totally excited about my new insurance for my small business. I am happy that the price was in a range that I can afford, the terms were easy to understand and it was so simple to purchase my first policy. I look forward to doing business with you in the future.
Curzella J.
Easiest insurance purchase – EVER!
I was looking around trying to compare insurance and I am so lucky I found ERGO NEXT. I was able to compare levels of coverage, and all the options, without pressure from a salesperson or time limits. I was able to check out prices and it was more coverage for less than the “traditional” company I looked at.
Michael W.
Happy small business owner!
I needed liability insurance for my new small business brick & mortar location. I got the run around from another company, but ERGO NEXT provided a competitive insurance quote in a timely manner. I now have the insurance that I need and it was stress-free!
Nicole E.
***The cost and claims data presented here are based on ERGO NEXT active customers in the U.S. who purchased business insurance in 2025. These data should not be considered a substitute for obtaining a quote specific to your business. These data were updated in August 2026.