Professional Liability Insurance
Protection from the costs of business mistakes and accusations of professional negligence
Choose your primary industry to get started:


What is Professional Liability insurance?
What can Professional Liability insurance cover?
- Business mistakes that cost a client money
- Claims of professional negligence
- Omissions or inaction that cause a client financial harm
- Legal defense costs if a client takes action
How much is Professional Liability insurance?
Starts at just $19/month†
Buy online in about 10 minutes, and cancel anytime.
Who needs Professional Liability insurance most?
- Professionals who require coverage for licensing or accreditation
- Business owners that sell advice or recommendations
- Purveyors of business services
- Professionals who plan, create or consult for other businesses
What could be covered by Professional Liability insurance?

Licensing and contract requirements
Some states, licensing boards and clients require professional liability coverage. Check with your licensing board and review your contracts closely.
The costs of business errors and professional mistakes
A client accuses you of a miscalculation or other business mistake that costs them money and you’re asked to cover their loss.**

Costs associated with professional negligence
One of your clients claims that an inaction or wrongdoing in your services, such as not filing a form or a missed deadline, caused them a financial loss.

The expense of defending yourself against misrepresentation
Someone who paid for your services accuses you of inaccurate information that caused them financial harm, such as relying on outdated tax code regulations.

Legal defense costs — even for unfounded accusations
You need to hire a lawyer to defend your business after you’re accused of a professional error, and professional liability coverage could help cover the cost.
Examples of small business Professional Liability insurance coverage protection
Professional liability coverage, also called E&O insurance (errors and omissions insurance) in some professions, may be required for some professional licenses in some states. It can also be required by clients to sign a contract.
Even if it’s not mandatory, a professional liability insurance policy could help protect your small business from unexpected costs associated with:
Accusations of professional negligence
Let’s say you’re an insurance agent or a home inspector. You feel that you did honest and thorough work for a client, but they claim that you didn’t share some property information and they take you to court for professional negligence. Even if it’s later found that you did nothing wrong, the legal battle draws out and the legal fees pile up.
Your professional liability insurance policy could cover some expenses around your legal defense up to the limits of your policy.
Business mistakes and errors
Imagine you’re a property manager and you make a mistake on some tenant paperwork that costs the property owner $50,000. The property owner sues you to get reimbursed for their financial loss.
Your small business professional liability coverage could help cover some of your expenses up to the policy limit.
How much does Professional Liability insurance cost?
Professional liability insurance policies can cost as little as $19/month for some low-risk businesses.
Several factors influence the monthly price you’ll pay for your business insurance, including:
- The industry that you’re in.
- The size and scope of your business operations.
- The state, city or county where you do business.
- The limits and deductible that you choose.
- Your years of experience in your field.
- Your history of business insurance claims.
How to get a Professional Liability insurance quote online

Start a free online quote
In about 10 minutes you’ll see the exact price you’ll pay for professional liability insurance online.

Customize your coverage
Adjust your policy limits and deductibles to pick the right coverage at the right price.

Buy 100% online
Your coverage is effective immediately after payment. And your certificate of insurance is ready at no extra cost.
Who needs business Professional Liability insurance?
Consultants
Your client may require that you have professional liability coverage to sign a contract. But even if it’s not a mandate, and even if you’re a business of one working from a home office, it could help protect your business from the costs of a professional error. Let’s say you create a campaign or an annual plan for a client and they build it based on your recommendation. Later they find that the data you pulled was inaccurate and that your strategy was flawed, costing them thousands in wasted investment and lost sales. Your professional liability insurance could help cover your business if you’re blamed for their financial losses and missed earnings.
IT professionals and digital content providers
If you work in information technology as a web designer, software developer, social media marketer or influencer — even if your business is just you and a laptop — a professional liability policy could help protect your business, and some clients may require it. If you build a proprietary system or database that accidentally deletes customer data during migration, your client could come after you for damages and lost revenue. Or if the social media content you post for your client damages their reputation and causes a financial loss, it’s possible that the company that hired you will tap you to recoup their losses. Your professional liability insurance could help with defense costs and covered damages, subject to your policy’s terms and conditions.
Accountants and financial advisors
If you’re a bookkeeper, tax professional or financial advisor, professional liability insurance (also known as E&O insurance) may be required for licensing. Even if it’s not a mandate, if your client accuses you of a mathematical error that led to an overpayment, they could seek damages and take action against you. If you have professional liability coverage, it could help cover some of your costs.
Engineers
In many states, a professional liability policy is a requirement for licensing and certification. But even where it’s not, it’s still a good idea to help protect your business interests. Let’s say a client claims that the materials you recommended to build out their retail space aren’t safe or adequate for their project. To rebuild, it will cost thousands plus weeks of lost income. Professional liability coverage for engineers could help to cover some of those expenses, and defense costs if they take you to court.
Architects
Architects can be required to have this type of business insurance to get a license or to keep their accreditation up to date. Even if it’s not mandatory where you work, this coverage could help protect your business during some client disputes that seek damages. Imagine a client alleges that your design error led to the collapse of a stairwell, and sues you for the injuries caused and the cost to rebuild. Your professional liability insurance coverage could help with the costs.
Professional Liability insurance cost calculator
See an estimate for your profession, then get a detailed quote for the exact price for your business
Where is your business located?


What do you do?
Businesses like yours typically pay:

Professional Liability insurance FAQ (frequently asked questions)
Is Professional Liability insurance legally required?
Professional liability insurance for small businesses can be a requirement for many professions, depending on your industry and your state laws. Industries commonly required to carry professional liability coverage include financial advisors, architects, engineers, lawyers and healthcare providers.
Errors and omissions insurance, also called E&O or E&O insurance, is another name for professional liability coverage. The insurance coverage is the same. E&O is commonly required for professionals working in real estate (including agents, brokers and appraisers), home inspectors, and for insurance agents and insurance brokers.
Be sure to check the requirements for your profession in your area.
Even if a professional liability policy is not required, if you work on high-cost projects, your clients may require you to carry insurance before they’ll let you submit a bid on a job, sign a contract or begin work.
Though professional liability insurance coverage may not be mandatory, it can signal your professionalism and help your business stand out amongst competitors. And, of course, it could be an asset for any business owner accused of a professional error or professional negligence.
How does Professional Liability insurance work?
If your business provides client services, expert advice or professional recommendations for hire, it’s likely you could benefit from professional liability insurance. In many cases it might be a requirement for licensing, license renewal or to work with some clients.
Even if you do everything right, a client might still make a legal claim that your work caused them financial harm — and legal costs to defend yourself would come out of your own pocket if you don’t have the right business professional liability insurance to help shield you from these costs.
This type of insurance can be especially useful for self-employed professionals and business consultants who are paid for their expertise or advice. In some fields, professional liability insurance can be required by law for client contracts.
What’s the difference between Professional Liability insurance and E&O insurance?
Professional liability coverage and errors and omissions insurance (E&O insurance) are often different names for the same kind of coverage. Both can help protect business owners if they’re accused of making a professional error or a professional omission that leads to a financial loss for a client.
The name of the policy can be different depending on your industry.
- Professional liability coverage is usually the choice for accountants, consultants, engineers and architects.
- Errors and omissions insurance is commonly used by real estate and insurance professionals.
What’s not usually covered by a Professional Liability policy?
Professional liability insurance coverage can provide help for a variety of situations, but it won’t protect you from all risks. Always check your policy for the full list of exclusions.
Here’s some examples of what professional liability insurance won’t cover:
- Intentional wrongdoing and illegal activity. Claims arising from intentional or fraudulent acts, or from knowingly violating the law, aren’t covered.
- Property damage or bodily injury. General liability insurance could help if your business is responsible for causing injury to someone who is not an employee or damaging property that doesn’t belong to you.
- False advertising. Professional liability won’t cover you if your marketing materials inadvertently contain misleading information and you’re sued for false advertising.
- Employee work-related injuries or illnesses. Workers’ compensation insurance could help cover medical expenses and lost wages if an employee is involved in a work-related injury.
- Car accidents. Commercial auto insurance may help cover expenses if you or your employees drive for business and get into an accident.
Can I add Professional Liability if I already have General Liability insurance or other coverage?
Yes, if you’re an ERGO NEXT policyholder with commercial general liability coverage or another policy, you can easily add professional liability coverage through your customer account.
Some small business owners may qualify for a discount on their total small business insurance package if they add multiple policies.
Does Professional Liability insurance cover my subcontractors and employees?
Your professional liability insurance policy could cover your employees, but only for the services they deliver for your business. It depends on the details of your specific policy. Subcontractors are not likely to be covered.
For example, if you own an architectural firm and one of your employees makes a project design mistake that causes costs to increase and timelines to double, your professional liability insurance could help cover your legal fees if the client sues your business.
Do you offer prior acts coverage?
Prior acts coverage depends on your industry and your business operations. We may provide prior acts coverage for businesses that have maintained continuous professional liability coverage at similar or higher limits since the requested retroactive date.
Can I add an additional insured to my Professional Liability policy?
Yes, ERGO NEXT customers can easily add an additional insured and share their certificate of insurance (proof of insurance, also called a COI) through their customer account.
When will I get my Professional Liability policy and proof of insurance?
It only takes about 10 minutes to get professional liability coverage 100% online with ERGO NEXT.
Answer a couple of questions about your business to get a free, no-obligation professional liability insurance quote specific to your business. You’ll choose your coverage, adjust the limits to fit your budget, and then buy coverage online — no agent required.
Your small business professional liability coverage is effective immediately after payment. And your shareable, unlimited certificates of insurance (COIs) as proof of your professional liability policy are available at no extra cost.
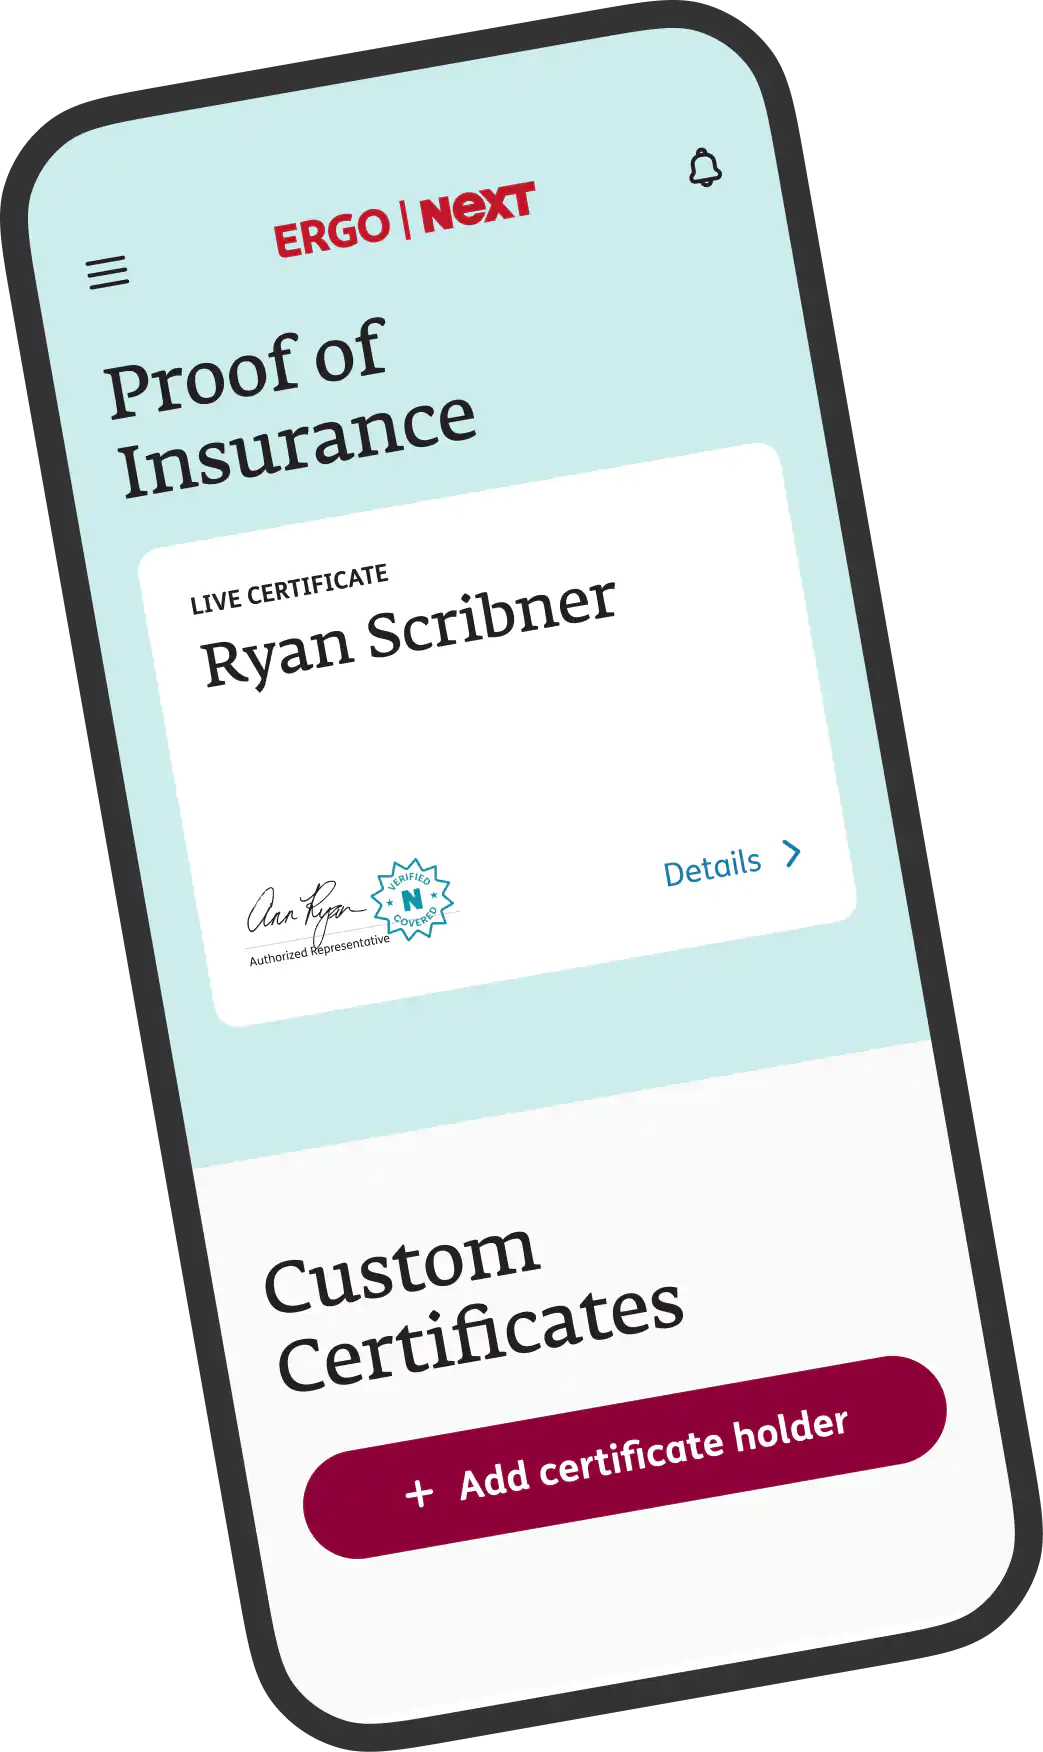
You’ll have immediate 24/7 online access to all of your policy documents online or on the ERGO NEXT Insurance app for iPhone or Android.
How do I make a Professional Liability insurance claim?
You can file a claim on your professional liability insurance policy anytime through your online account or in the ERGO NEXT Insurance app.
You’ll be asked to share the details of what happened and to provide relevant photos and documentation. We strive to make claims decisions as quickly as possible so that you can get back to work.
Compare Professional Liability insurance
We’ll walk you through the differences and similarities between professional liability insurance and other types of coverage to help you make the best choice for your business.
Get customized insurance wherever you do business
Learn more about professional liability insurance options in the state where you work.
ERGO NEXT Insurance reviews


There’s a lot to love about ERGO NEXT

Get insurance in less than 10 minutes and you can save up to 25% in discounts*

Unique, flexible coverage with easy monthly payments

Do it all 100% online or talk to a licensed U.S.-based advisor
Coverage on-the-go for policyholders
Manage your policies, send and create certificates of insurance, or file a claim with our app.

