NEXT is now ERGO NEXT Insurance, uniting digital-first innovation with Munich Re's global financial strength.

Hawaii Business Insurance

Save on business insurance Hawaii with discounts up to 25%*

What could be covered by Hawaii business insurance?

Property Damage

Property damage, including products and inventory

If a landscaping business in Oahu accidentally damages a client’s home, or a gift shop in Kailua suffers a fire, business insurance could help cover the damages.**

Injuries

Medical payments for injured customers or employees

An electrician in Pearl City injures their back on the job, or a cafe customer in Hilo slips on a wet floor. Small business insurance could help cover medical bills, legal costs, job retraining and more.

Inventory

The fallout of theft, burglary and vandalism

A Kauai spa gets its windows shattered and all its products stolen. Hawaii business insurance could help cover costs and lost income during repairs.

Advertising Harm

Lost wages and business income

An employee is injured on a job site in Honolulu. Business insurance could help with medical bills and wage replacement while they recover. And it could replace business income after a covered event like a fire or storm damage.

Costs after a professional mistake or workmanship error

If a consultant, accountant or other professional service provider makes a professional miscalculation, misses a deadline or uses the wrong materials and it costs their client money, business insurance could help.

Legal fees

Legal fees and defense costs

Business insurance in Hawaii could help if you need an attorney to defend your small business in a lawsuit after a claim, or if you need financial help for court fees, judgements and settlements.

Is Hawaii business insurance required by law?

Yes, some types of small business insurance policies in Hawaii are required for small business owners, including workers’ compensation insurance for almost all businesses with employees, and general liability insurance for contractors and other related industries for their professional license.

Even if your business is not required to carry a specific type of business insurance by state law, some clients, commercial landlords, financial lenders, municipalities, vendors or event spaces may require proof of business insurance coverage (called a certificate of insurance, or a COI) before they’ll do business with you.

Mandatory business insurance: Hawaii Workers’ Compensation insurance

According to the Hawaii Department of Labor and Industrial Relations, most businesses with one or more employees are required to carry workers’ compensation insurance. This includes full-time and part-time employees, as well as permanent and temporary workers.

There are some exceptions, including certain real estate salespeople and brokers who are paid solely on commission, certain business owners and some domestic, nonprofit and religious workers.

Other mandatory requirements for Hawaii business insurance

Other Hawaii small business insurance requirements can vary by profession and license. For example, licensed contractors must maintain general liability insurance throughout their licensure. The Hawaii Contractors License Board also requires contractors to maintain workers’ compensation coverage unless they qualify for an exclusion.

Even if coverage isn’t required by Hawaii law, most small business owners could benefit from the financial protection of business insurance.
How much does Hawaii business insurance cost?

The cost of small business insurance in Hawaii can depend on a number of factors, including the type of protection your business needs and your business’ level of risk.

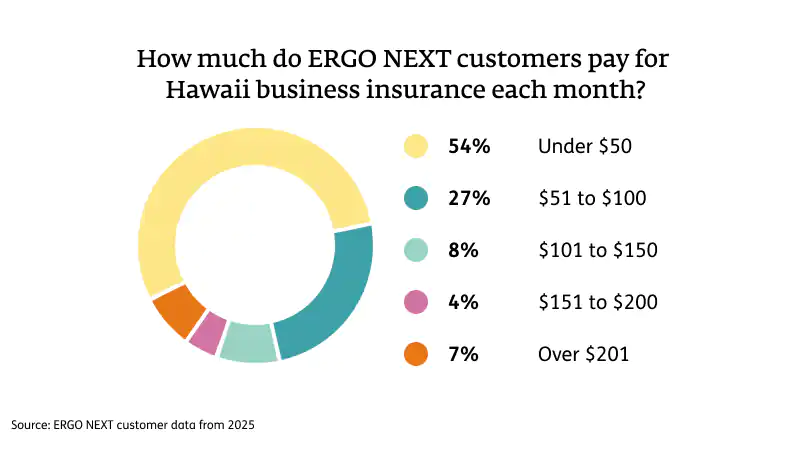
At ERGO NEXT Insurance, some low-risk business owners spend as little as $19 per month† for a single policy. And more than half of the businesses that we insure in Hawaii — 54% — spend under $50 per month for their total coverage.

For general liability insurance, which is the most common type of business insurance bought by Hawaiian ERGO NEXT customers, the median cost for liability coverage is just $42 per month.

81% of Hawaii small business owners insured by ERGO NEXT spend $100 or less per month for business insurance.

The monthly or annual premium you’ll pay for your business insurance in Hawaii depends on a number of factors related to your business risk, including:

  • Your industry. Jobs that are higher-risk, such as construction, often have higher insurance costs than lower-risk desk jobs, such as an accountant.
  • The number of employees you have. With Hawaii’s mandate that you carry workers’ comp coverage if you have one or more employees, your business insurance could cost more if you’re covering a team rather than a single worker or just covering yourself as a sole proprietor.
  • The location of your business. If you’re in a more densely populated city like Honolulu, you may pay more for business insurance than if you operate a business in a smaller town like Waimea.
  • Your years of work experience. A proven history of workplace safety and success in your industry can impact your insurance rate. A new business owner could pay more than a veteran in their field.
  • Your insurance claims history. Your record of safety, losses and claims could have an impact on your insurance premium.
  • The insurance coverage limits you choose. Higher insurance coverage limits on your policy could offer more protection over more risks. But it could also increase the cost of your business insurance.

The best way to know exactly what you’ll pay for business insurance is to check prices for your business. It takes about 10 minutes, and you can do it 100% online.

Which types of business insurance policies do Hawaii business owners buy most often?

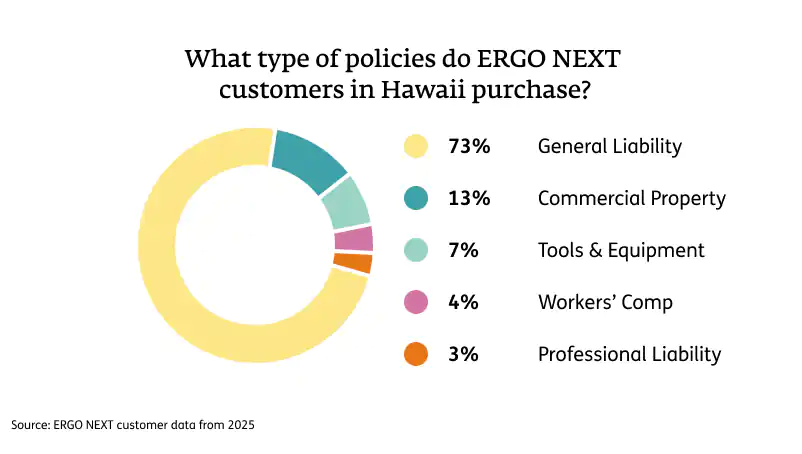
General liability insurance is our most common small business insurance policy in Hawaii: 73% of total active ERGO NEXT policies in Hawaii are general liability.

Customers with this coverage could have some protection from accidental property damage caused by their business and medical costs for non-employees who get hurt at their place of business.

Though this type of coverage isn’t mandated by the state, it’s often required to start or grow a business. Many business partners, such as landlords or lessors, as well as loan officers, vendors or clients, require a business to carry commercial general liability coverage.

You may need general liability coverage in order to:

  • Get and maintain a professional license.
  • Qualify for business financing.
  • Sign a lease on a commercial storefront, office, warehouse, workshop, storage facility or building.
  • Submit a bid for a job.
  • Participate as a vendor in an event space, like a pop-up or a farmers market.
  • Begin work on some contracts.

The second-most popular type of small business insurance in Hawaii is commercial property insurance. This is an essential type of coverage for small businesses that own physical property or lease a commercial space — even if you run your business from home.

Commercial property insurance coverage could help cover costs for the property you use for business, including your building structure, business furniture, flooring, lighting, business equipment like laptops and computers, products and inventory.

73% of the active policies that ERGO NEXT customers have in Hawaii are general liability insurance.1

Which types of business insurance in Hawaii could benefit your business most?

Business owners who buy small business insurance Hawaii often bundle several types of commercial coverage for greater protection. Depending on your business insurance needs, common policies could include:
General Liability

Hawaii General Liability insurance

Commercial general liability coverage is one of the most important types of insurance for small businesses. Some commercial landlords in Hawaii may ask that you have general liability coverage before you can sign a lease. It’s also common for clients to require this liability coverage before they’ll sign a contract with your business.

This type of business insurance could provide protection from the costs of many common incidents, like if a non-employee gets hurt at your business or if you or one of your employees causes damage to someone else’s property.

In such situations, a general liability policy could cover medical bills, repairs or replacements, and legal fees to defend your business.

For example, an apartment complex owner accuses a Hilo dog walker of destroying a flower bed on the job. General liability coverage could help the dog walker pay for the property damage.

Cleaning businesses and contractors can add optional tools and equipment insurance to their Hawaii general liability policy. This coverage could help replace important business gear if it gets stolen.

Learn more about general liability insurance in Hawaii.
Workers Compensation

Hawaii Workers’ Compensation insurance

State law requires most businesses with even just one employee to carry Hawaii workers’ comp insurance. This kind of coverage could help cover costs associated with employee job-related injuries, such as medical bills, rehabilitation costs and lost wages during recovery.

For instance, an employee of a Maui event planning firm sprains a wrist staging a conference and requires several doctor visits and physical therapy. Medical professionals recommend that the employee take two weeks off work to recover from the work-related injuries.

Workers’ comp insurance could help pay for the injured employee’s medical bills and cover a portion of lost wages until they’re able to work.

Learn more about workers’ compensation insurance in Hawaii.
Commercial Auto

Hawaii Commercial Auto insurance

Hawaii small business owners with company-owned vehicles may be required to carry commercial auto insurance. This coverage could help protect your business if an accident happens while you or an employee are driving for work.

If a handyman in Hilo collides with another car, commercial auto insurance could help cover the other driver’s vehicles and medical expenses related to the incident.

Learn more about commercial auto insurance.
Commercial Property

Hawaii Commercial Property insurance

Hawaii commercial property insurance could protect your business property, including products, inventory and your actual physical building. You could also collect business income if you have to close temporarily for repairs after a covered event like a broken water pipe or heavy story damage.

With this type of coverage, you could get help with costs after a covered event, such as vandalism, theft or fire.

For example, a grease fire at a Pearl City diner damages kitchen appliances, countertops, cabinets and cookware. Commercial property coverage could help cover the costs for the kitchen gear that was destroyed.

Learn more about commercial property insurance in Hawaii.
Errors & Omissions

Hawaii Professional Liability insurance

Professional liability insurance, also called E&O or errors and omissions insurance in some industries, could help cover damages if someone claims they incurred financial losses because you made a professional mistake or missed a deadline.

For example: If a Wailea hotel owner claims that their accountant made a property tax error that resulted in significant fines, the accountant’s professional liability insurance could help pay for the financial damages and attorney fees, court costs and settlements.

Even if your professional services aren’t found to be at fault, your business could still face the cost of a legal defense. And professional liability coverage could help.

Learn more about professional liability insurance in Hawaii.

Get custom business insurance with ERGO NEXT in about 10 minutes, 100% online

Why choose ERGO NEXT for Hawaii business insurance?

ERGO NEXT makes it fast, easy and affordable to get Hawaii business insurance coverage customized for your business in about 10 minutes, 100% online.

Manage your policy 24/7 via web or mobile app, and get unlimited, sharable certificates of insurance (proof of insurance) at no extra cost.

If you have questions, our U.S.-based licensed agents are available to help.

Hawaii Business Insurance FAQ

Find answers to some of the most frequently asked questions about small business insurance in Hawaii.

What happens if a business doesn't have Hawaii small business insurance?

There can be legal consequences if you fail to carry business insurance that’s required by the state. According to the Hawaii Department of Labor and Industrial Relations, if an employer is required to provide workers’ compensation insurance and they fail to do so, they can face a penalty of at least $500 or $100 per employee for every day without coverage.

Licensed contractors without business insurance can also face consequences. The Hawaii Contractors License Board states that failure to maintain required liability and workers’ compensation insurance could result in the automatic forfeiture of a contractor license.

If you own a business in Hawaii and you don’t carry the right business insurance, you could lose out on business opportunities and growth opportunities like work contracts, commercial leases, financing or other opportunities that require proof of coverage.

Do independent contractors need Workers’ Compensation insurance in Hawaii?

Hawaii generally requires employers with one or more employees to provide workers’ compensation insurance. Businesses shouldn’t assume that just because they call someone an “independent contractor” it eliminates their responsibility to provide workers’ compensation coverage. Employee classification law may still consider some of these workers to be employees.

The Hawaii Department of Labor and Industrial Relations provides more information on the legal meaning of independent contractors, workers’ compensation requirements and employee exemptions to the mandate.

Do Hawaii contractors need liability insurance?

Yes. Licensed contractors in Hawaii are required to maintain liability insurance throughout their licensure.

According to the Hawaii Contractors License Board, contractors must also maintain workers’ compensation coverage unless they qualify for an exclusion. Failure to maintain required coverage can result in automatic forfeiture of your contractor license.

Does Hawaii require every business to carry General Liability insurance?

Many professions and professional licenses in the state of Hawaii do require general liability coverage. Licensed contractors, for example, must maintain liability insurance as a condition of licensure. Clients, landlords and other businesses may also require general liability insurance before a business owner can sign a contract or lease.

However, Hawaii doesn’t have a blanket statewide requirement that every small business must carry general liability insurance.

Could my Hawaii business insurance cover hurricane damage?

Your small business insurance could cover hurricane damage in Hawaii, but it depends on your policy and the cause of the damage.

Hurricanes can cause losses from wind, rain, flooding and other hazards, and different types of damage may be treated differently under an insurance policy.

The Hawaii Insurance Division recommends reviewing your property insurance coverage and deductibles before hurricane season. Check your commercial property policy carefully to see what hurricane-related damage could be covered.

Which types of business insurance claims do Hawaii businesses file most often?

The Hawaii industries that we insure with the most claims activity include (in order):

  1. Handyperson
  2. Landscaping and lawn care
  3. House cleaning

ERGO NEXT Insurance reviews

I am so excited
I am totally excited about my new insurance for my small business. I am happy that the price was in a range that I can afford, the terms were easy to understand and it was so simple to purchase my first policy. I look forward to doing business with you in the future.
Curzella J.
Easiest insurance purchase – EVER!
I was looking around trying to compare insurance and I am so lucky I found ERGO NEXT. I was able to compare levels of coverage, and all the options, without pressure from a salesperson or time limits. I was able to check out prices and it was more coverage for less than the “traditional” company I looked at.
Michael W.
Happy small business owner!
I needed liability insurance for my new small business brick & mortar location. I got the run around from another company, but ERGO NEXT provided a competitive insurance quote in a timely manner. I now have the insurance that I need and it was stress-free!
Nicole E.
1 The cost and claims data presented here are based on ERGO NEXT active customers in the U.S. who purchased business insurance in 2025. These data should not be considered a substitute for obtaining a quote specific to your business. These data were updated in August 2026.