Can you store business inventory at home?
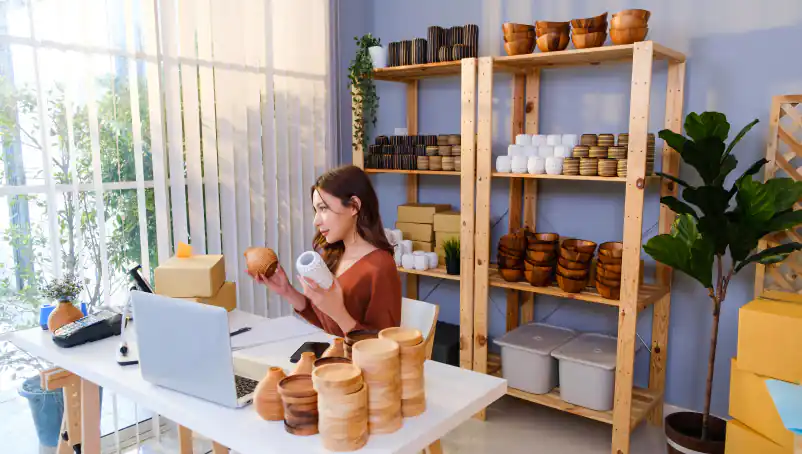
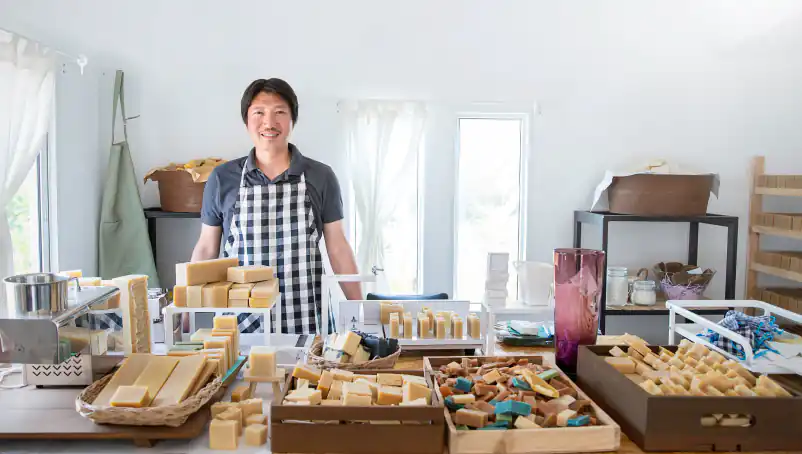
Whether you’re selling handmade soap on Etsy or packing Shopify vintage clothing orders from your spare bedroom, storing inventory at home is usually the simplest and most affordable option for small business owners. It keeps overhead low and makes orders easy to fulfill.
But as your business grows, so does your stuff. A few boxes in a closet turns into shelves in the garage. Before you know it, you’ve got thousands of dollars of inventory sitting under the same roof as your personal belongings.
Your business may not be running out of storage space. But more inventory can mean more financial risk — especially if products get damaged, stolen or destroyed. And homeowners insurance may not provide adequate coverage for business property.
What type of business inventory can I store at home?
Generally, inventory that’s small and lightweight is well-suited for home storage.
However, some products may require special storage conditions based on local zoning laws, homeowners association (HOA) rules or rental agreements. Depending on the terms of the living space you own or rent, your home business may have limits on:
- The amount of inventory you’re allowed to store
- Hazardous material storage
- How much customer or vendor traffic your home business receives
- The amount of commercial deliveries you can receive
- How much exterior storage you’re allowed for your business
Be sure to check the local rules of your state, city, county, HOA, neighborhood or apartment complex to ensure that your business is compliant.
What are the biggest risks of storing business inventory at home?
For many home businesses, storing inventory at home is the easiest option — until something unexpected happens. Maybe a frozen pipe bursts while you’re away. Or someone breaks into the garage and steals all of your products. Or your HVAC system stops working and you lose several batches of homemade products, like soap or candles or chocolate, that need to be kept cool.
Here are some of the biggest risks to the business products you store at home to keep in mind.
1. Fire and smoke damage
House fires are rare, but they can be devastating. Even if the fire never reaches your inventory, smoke damage can ruin products stored in garages, basements or spare rooms.
If you sell flammable products like candles or aerosol sprays, they’re especially prone to damage.
2. Water damage
Water has a way of finding inventory. It’s a common threat to products stored inside a home business. An open window, a leaking roof or a burst pipe can soak cardboard boxes and damage products long before you notice a problem.
3. Theft or burglary
The more inventory you keep at home, the more valuable your property may become to thieves. Packages left near the front door could attract “porch pirates.” And unlocked garages with visible stacks of boxes can make your home a more attractive target.
A break-in can mean replacing products, delaying customer orders and losing revenue while you rebuild your inventory. For businesses that rely on quick shipping, even a relatively small theft can severely disrupt your operations — and your growing reputation.
4. Running out of space
Sometimes the biggest challenge isn’t a fire or theft — it’s simply running out of room. As your business and inventory grows, it’s easy for boxes to (uncomfortably) spread into living spaces.
If your homeowners insurance can’t help you with any of the above scenarios, you could be left paying out of pocket for all damaged inventory yourself.
Does homeowners insurance help protect home business inventory?
If you run your business from home, you might assume your inventory is covered by the same homeowners policy you have to protect your personal stuff. But homeowners insurance is generally designed to protect your home and personal belongings — not the products you sell as part of a business.
While some homeowners policies might provide some coverage for business property kept at home, it’s pretty limited. And certain types of losses or inventory may not be covered at all.
How much business property your homeowners insurance will cover depends on your policy. Some homeowners policies include limited coverage for business property kept at home, but those limits may not go very far if you’ve built up thousands of dollars’ worth of inventory.
According to the Insurance Information Institute, standard homeowners policies often cap business property coverage at a low dollar amount, commonly around $2,500, though limits vary by insurer and policy. If your inventory is worth significantly more than that, you could be left paying the difference out of pocket after a covered loss.
Coverage also depends on the cause of the damage. And certain types of losses or business property may be excluded.
How insurance companies differentiate personal property from business property for a home business
Your one laptop may be your bookkeeping system by day, and how you binge on Netflix by night. That’s normal for many sole proprietors. But when it comes to insurance protection, that’s also where things get complicated.
Insurance policies often have a hard line between what’s personal property and what’s business property, even when you’re using the same belongings for both.
Maybe you started making handmade candles for friends and family, but then your hobby became a business. You started selling on Etsy. Before long, half the garage was filled with inventory.
Insurance companies consider factors like:
- Whether you’re selling products for profit
- How much inventory you keep on hand
- Whether your business is ongoing
As your business grows, inventory that once felt like a personal hobby can become business property instead.
Which types of business insurance could help protect a home business?
If you run your business from home by yourself and you don’t have customers coming to your door, commercial property insurance could help protect the physical things your business depends on — including products and inventory.
If your inventory is damaged by a covered event like a fire, burst water pipe, heavy storm damage, a burglary or vandalism, commercial property insurance could help cover the costs, depending on your policy.
A commercial property insurance policy usually includes several types of coverage that work together to help protect your home business, including:
Goods, gear and inventory protection. Sometimes called business personal property insurance, this is the coverage many home-based retailers think about first. It can help cover your business property, including inventory, equipment, business furniture and other business belongings if they’re damaged or stolen in a covered loss.
Business income coverage. If a covered loss forces you to temporarily shut your business down for repairs, business income coverage (also called business interruption insurance) could help replace your lost business income while you recover. It may also help cover some extra expenses, such as moving to a temporary location so you can continue serving customers.
An optional add-on for equipment breakdowns. Sometimes a power surge or mechanical failure can damage the equipment your business relies on every day. Equipment breakdown coverage could help if covered business equipment is damaged by certain types of mechanical or electrical failures. For some home businesses, that could include computers, label printers, packaging equipment or refrigeration used to store products.
Consider a Business Owner’s Policy (BOP insurance)
Many small retailers and e-commerce businesses choose a Business Owner’s Policy, also called BOP insurance because it combines commercial property insurance with general liability insurance into one convenient policy that’s often more cost-effective than buying two separate policies.
While commercial property insurance can help protect your inventory and business belongings, general liability insurance could help cover claims if someone says your business caused a physical injury, property damage or advertising injury.
8 ways to store business inventory safely at home
Storing inventory at home doesn’t have to mean sacrificing your living space — or putting your products at unnecessary risk. A few smart habits can help keep your inventory organized and better protected as your business grows.
1. Create a dedicated storage space
It might be tempting to stash products wherever there’s room, but that’s a recipe for misplaced inventory.
Whether it’s a spare bedroom, basement or one corner of the garage, keeping inventory in one dedicated area makes it easier to stay organized. You can track products and fulfill orders without turning your whole house into a warehouse.
2. Store products off the floor
After a burst pipe, where does water end up? The floor.
Use sturdy shelving, racks or pallets to keep inventory elevated, especially in garages and basements. Plastic storage bins can also provide more protection than cardboard boxes for storing products long term.
3. Control temperature and humidity
Extreme temperatures can shorten the life of some products before they ever reach a customer.
If you sell candles, cosmetics, supplements, electronics, paper goods or other temperature-sensitive items, try to store them in a climate-controlled part of your home. Temperatures in garages, attics and sheds can fluctuate widely throughout the year.
4. Keep business inventory separate from personal belongings
When holiday decorations, camping gear and business inventory all share the same shelves, it’s easy to lose track of what’s what. Keeping business inventory in its own clearly marked space makes counting stock, packing orders and documenting losses much easier if something goes wrong.
5. Improve your home’s security
As your inventory grows, so does its value. Start with simple security measures:
- Lock storage areas
- Install motion-sensor lights or a security camera
- Keep inventory out of sight from windows
- Bring deliveries inside quickly or opt for a pickup at a secured location
6. Keep track of your inventory
You don’t need expensive software, but you should always know what you have in stock. Whether you use a spreadsheet, an inventory management app or an e-commerce platform, keeping accurate inventory records can help you avoid overselling and spot missing items.
If products expire or have seasonal demand, organizing them using a first-in, first-out (FIFO) system can help reduce waste and keep older inventory moving.
7. Save receipts and document your inventory
Good records can save you a lot of frustration later. Keep receipts, supplier invoices and photos of your inventory, especially as your business grows. If inventory is damaged or stolen, having documentation can make it easier to calculate your losses and support an insurance claim.
8. Review your insurance as your business grows
The business insurance coverage from when you were selling a handful of products may not be adequate after your business takes off.
As your inventory becomes more valuable, review your homeowners insurance and your business insurance regularly to make sure it’s enough to cover current risks to your products. The goal is to make sure your insurance coverage is keeping up.